
The $58 Session and the $205 Bath: Othership and AIRE Are Building Opposite Models in the Same Neighborhood
By Arlene Scott
Senior Wellness Correspondent & Hospitality Consultant
- Published
- Updated
- Reading time
- 10 min
SaunaNews is published by SaunaShare, Inc., which also runs SaunaShare.com and SaunaMarketplace.com, where we sell many of the products we write about. Assume that experience shapes what we cover and what we don't. Who owns SaunaNews · The ownership announcement
Two thermal wellness operators ten minutes apart in downtown Toronto offer a clear case study for the industry: high-frequency programming versus low-frequency luxury, venture capital versus patient capital, and why the model you choose determines everything about your business.
In this story5 sections
Two thermal wellness operators sit roughly ten minutes apart in downtown Toronto. One charges CAD $58 per session and packs its Toronto saunas with up to 90 people at a time. The other charges CAD $205 for a 90-minute bath circuit and caps sessions at its London and New York baths at 14 to 20 guests. One has raised about $18 million from investors and wants to open in cities across North America. The other is a privately held Spanish company that generated €69.4 million in revenue in its fiscal year ended June 2023, at a 36% EBITDA margin.
Othership and AIRE Ancient Baths are not competing for the same customer. They are running fundamentally different businesses that happen to share a category and a neighborhood. For anyone building, investing in, or programming thermal wellness over the next decade, the gap between these two models is the most important thing to understand about where this market is heading.
- Othership Toronto. Began in 2019 as a backyard ice bath; first bathhouse opened in 2022. Five co-founders including CEO Robbie Bent. Four locations open (two Toronto, two NYC). CAD $58 drop-in, memberships from USD $51/month in New York. Raised about $18M across seed, Series A, and SAFE rounds.
- AIRE Ancient Baths Founded in 2001; first bathhouse opened in Seville in 2004. Ten locations across five countries. Toronto opened December 2025 at 510A Front Street West (23,000 square feet). 90-minute bath experience in Toronto: CAD $205. FY2023 revenue: €69.4M, EBITDA margin 36%. 1,100+ employees.
- Why it matters These two operators represent the clearest available case study in thermal wellness economics: high-frequency/high-density versus low-frequency/high-margin. The model an operator chooses determines capital structure, staffing, retention mechanics, and saturation risk.
The Othership model: volume, programming, and ritual
Othership started in 2019 as an ice bath in Robbie and Emily Bent’s Toronto backyard. When the weather turned cold, they converted the garage into a sauna and ice bath, Robbie Bent told Culture of Bathe-ing. He built the company with four co-founders: Emily Bent, Amanda Laine, Harry Taylor, and Myles Farmer.
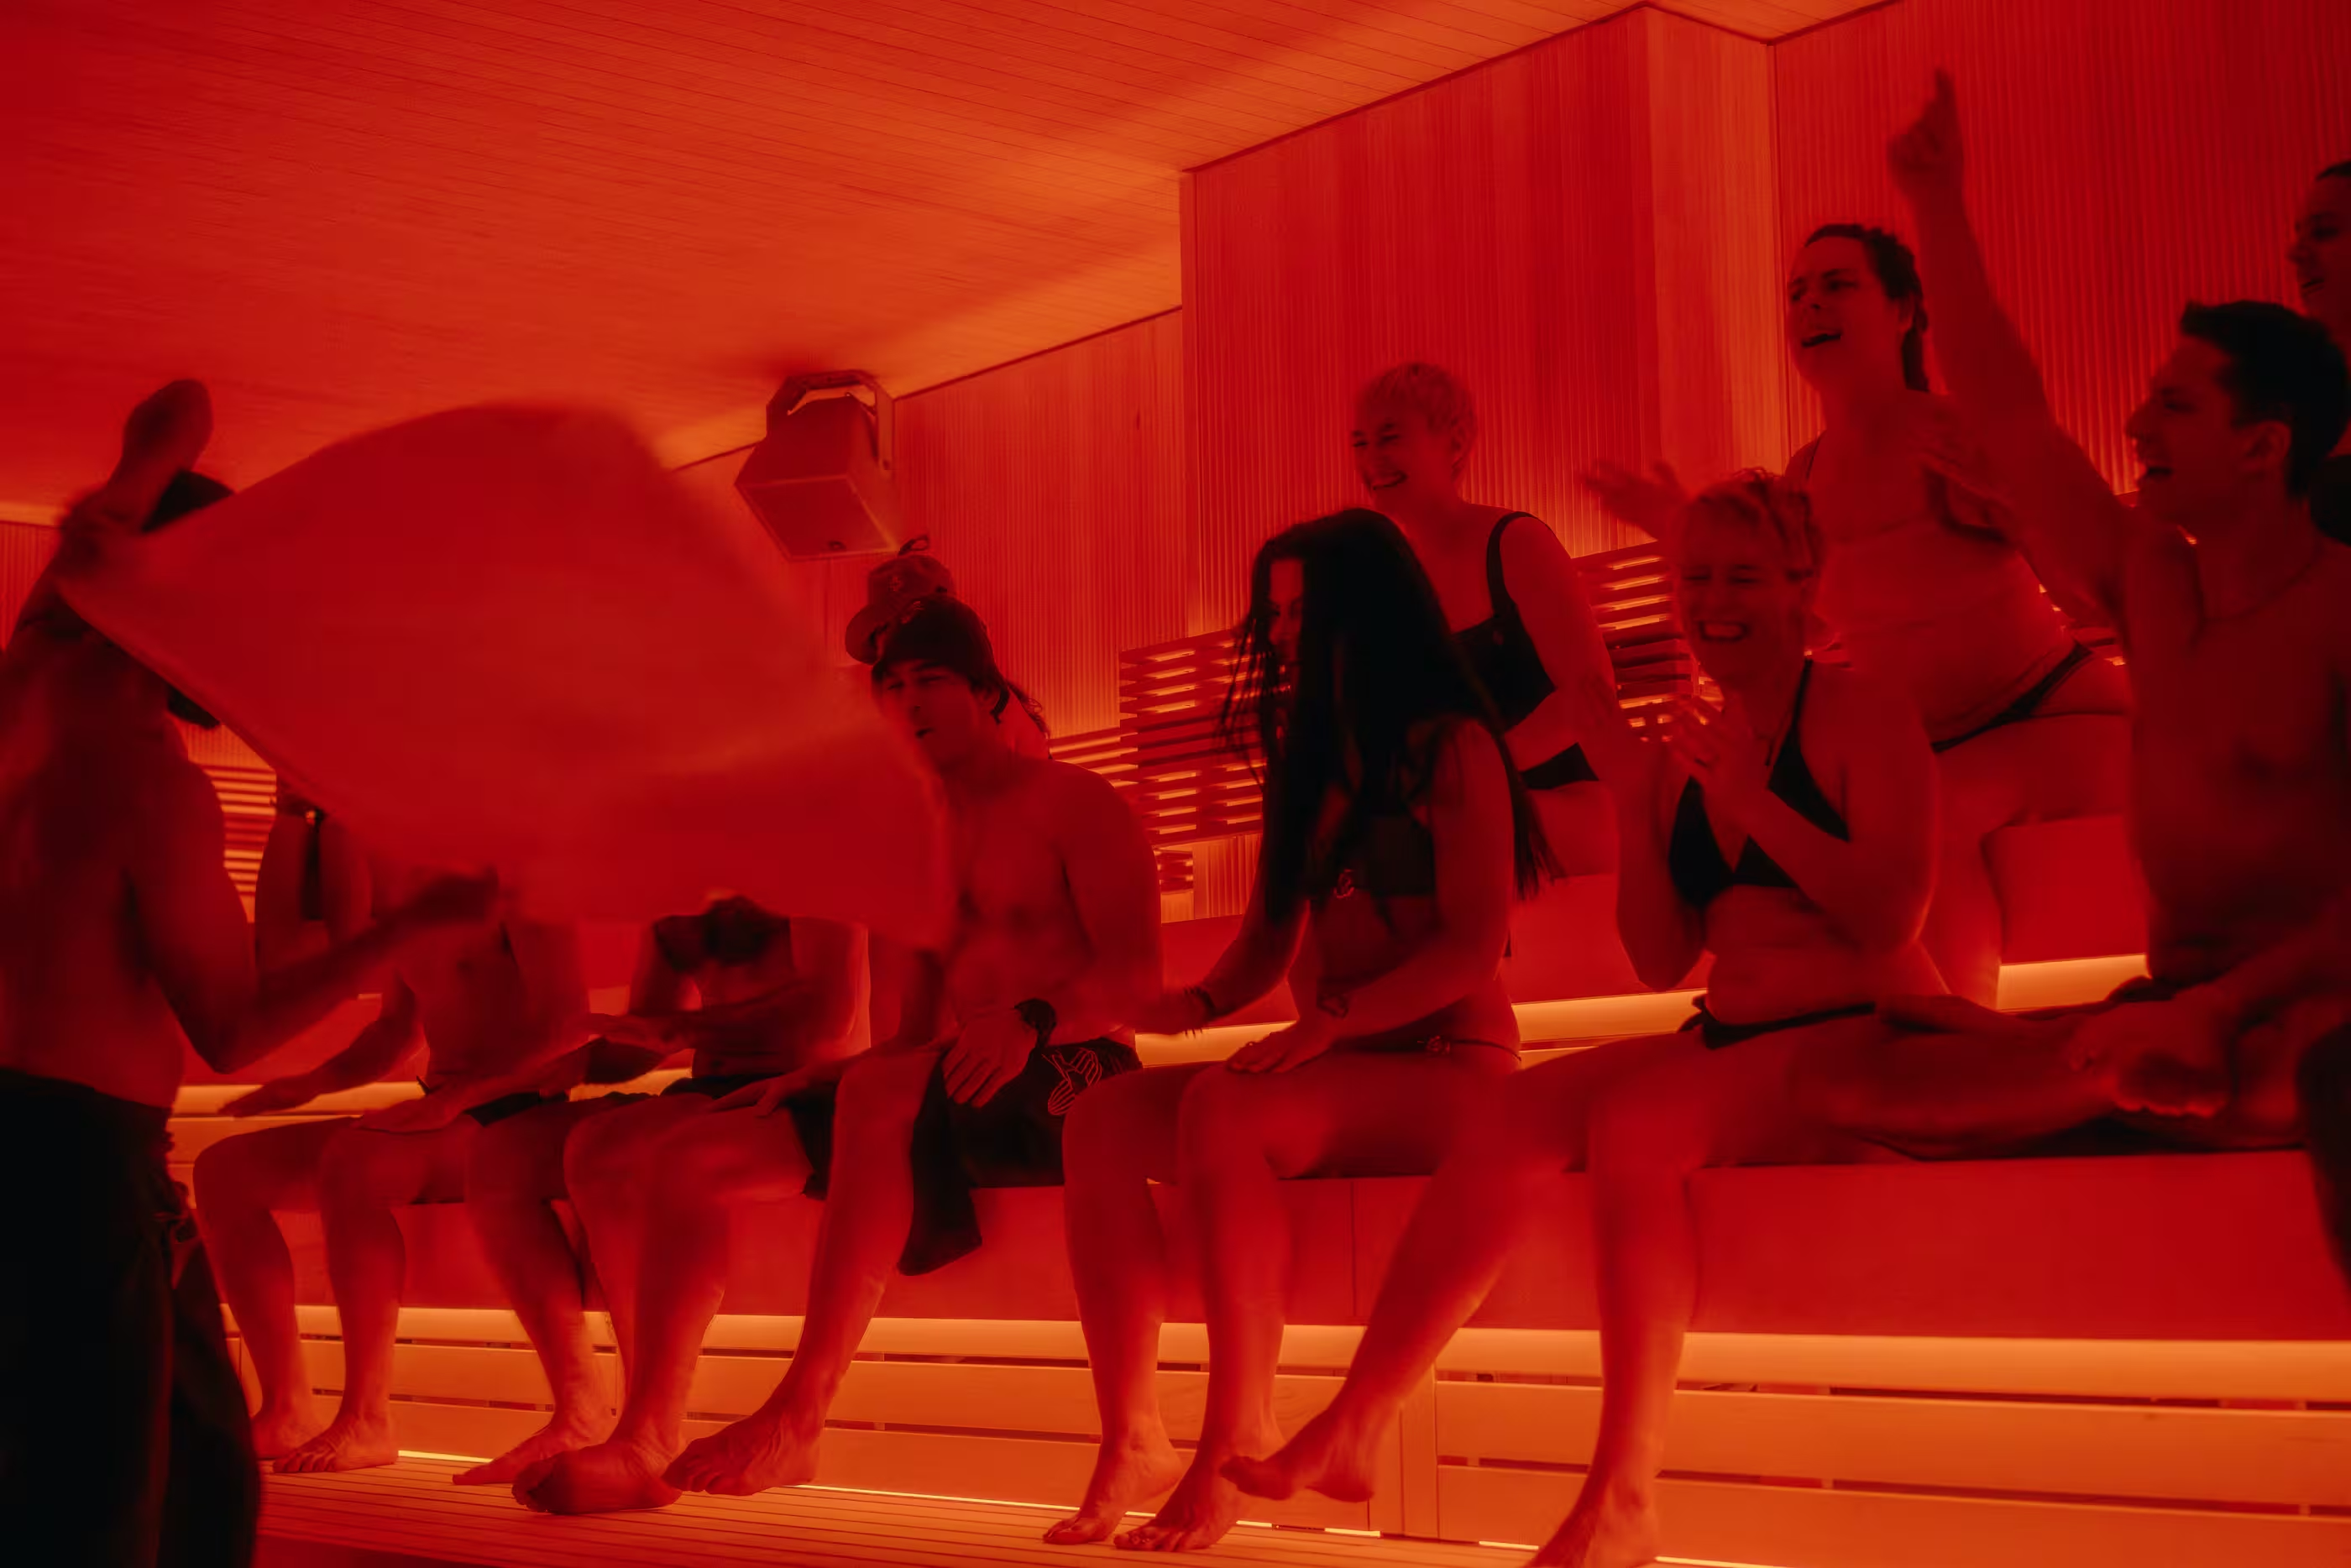
The business model is closer to a fitness studio than a spa. The Toronto flagship on Adelaide Street occupies roughly 3,000 square feet, with a sauna that holds about 50 people. The second Toronto location in Yorkville, which opened in late 2023, is larger, with a 90-person performance sauna and eight ice baths. The New York Flatiron location, which opened in July 2024, spans more than 7,000 square feet and also has a 90-person sauna, which Othership billed as the largest in the US, according to Spa Business. A Williamsburg location followed in September 2025 (6,168 square feet on a 10-year lease at 25 Kent Avenue), and an Upper East Side location of 14,000 square feet is announced for 2027.
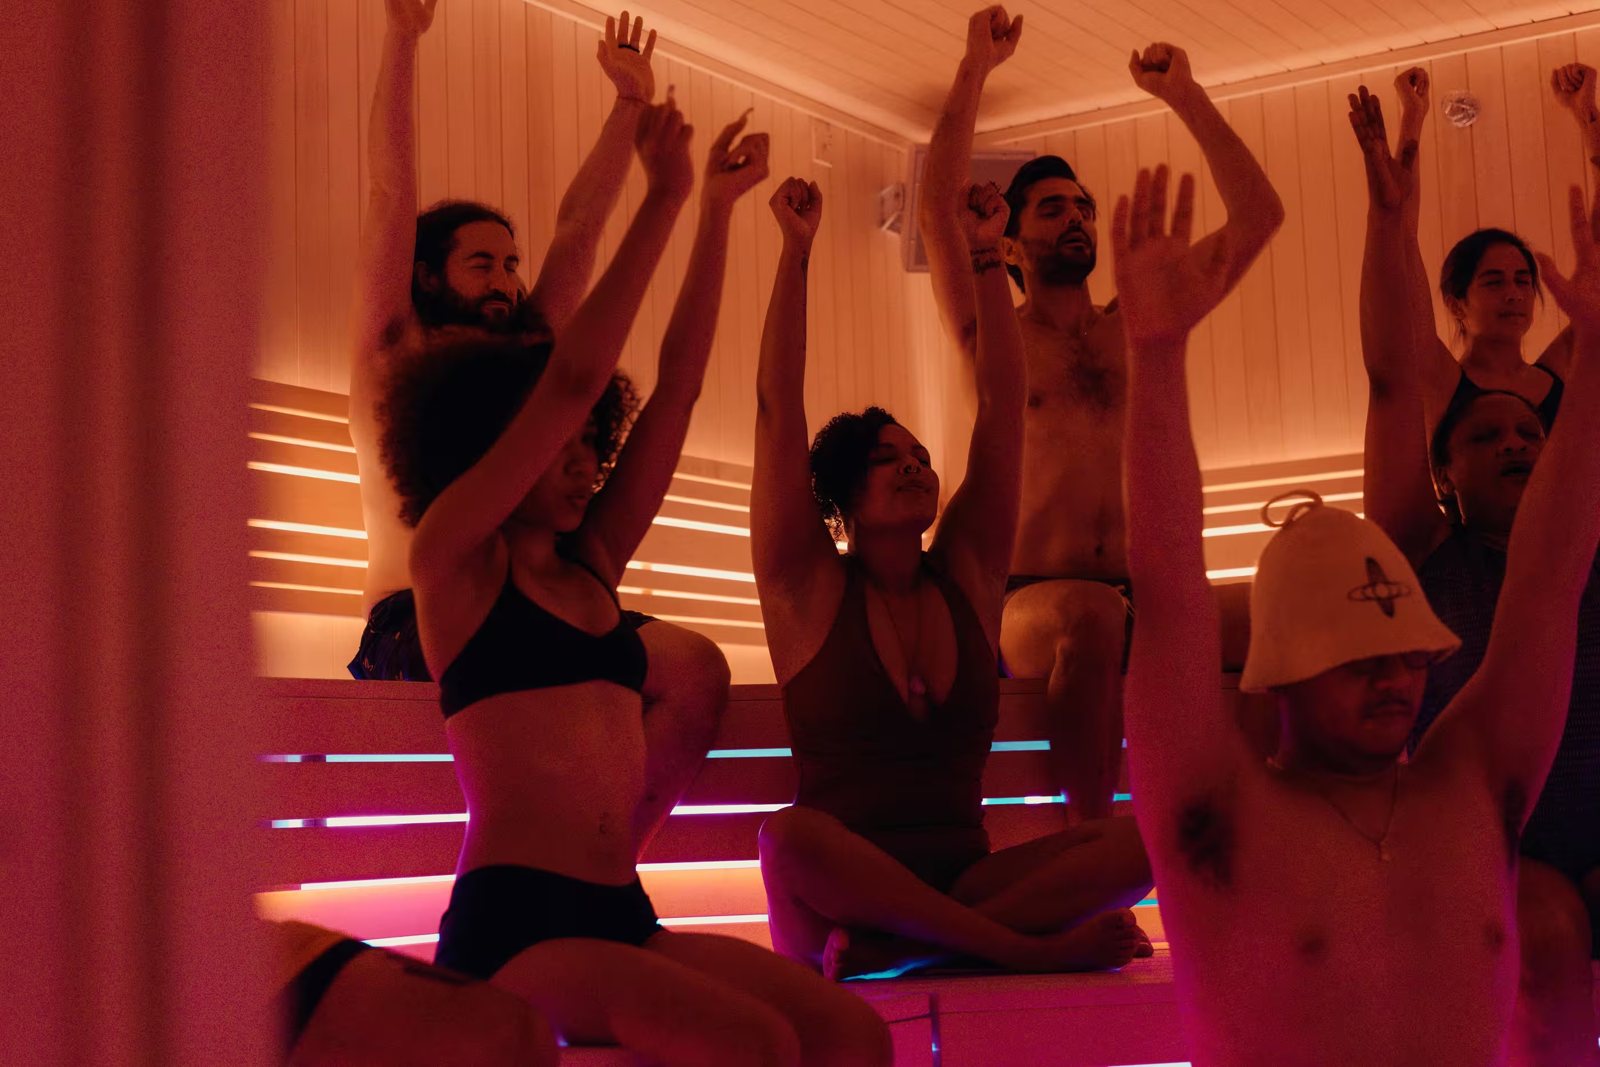
What fills those rooms is not heat alone. Othership runs guided sessions that combine breathwork, vocalization, visualization, and music inside the sauna, followed by cold plunges. The company frames these as “journeys,” not treatments. Facilitators lead the room. The programming is the product.
This is the same insight that drives Bathhouse’s push toward a $120 million revenue run rate and the aufguss playbook we have covered before: the sauna becomes a stage, and the operating margin comes from selling a repeatable ritual at high throughput. A 90-person sauna running four guided sessions a day at $58 per head produces a very different P&L than the same room rented out for passive soaking.
Othership charges CAD $58 for a drop-in session in Toronto, Narcity reported in March. In New York, a single session costs USD $64, or $46 for a weekday session before 4:30 p.m., and memberships start at USD $51 per month for one session a month, according to Othership’s price list. First-timer packs start at $135 for multiple sessions. Class packs scale up to $3,600 for 100 sessions. The pricing is designed for repeat visits. The unit economics depend on it.
At $58 per drop-in, Othership needs bodies in seats multiple times a week, not once a quarter. The membership tier, the class-pack ladder, and the sober-social positioning (no alcohol, and no phones past the entrance and common area) all point toward one goal: make the sauna a habit, not an occasion.
The AIRE model: scarcity, heritage, and margin
AIRE Ancient Baths runs the opposite calculation. The privately held Spanish company (registered in Granada, run from Barcelona, and controlled by its three co-founders, Armando Prados, Amós Milton García, and Adrián Martínez, who held most of the capital among 21 shareholders in 2023, according to La Vanguardia) has spent more than two decades building a global network of thermal bath facilities inside heritage buildings. CEO Amadeo Serra, a former Fluidra executive whom the owners hired around 2016 to professionalize management, has led the expansion.
The first AIRE location opened in 2004 inside a 16th-century Mudejar palace in Seville that contained actual Roman-era baths. The model has since expanded to Barcelona (18th-century food warehouse), Almería (on the square that once held the city’s Arab souk), Vallromanes (a farmhouse dating to 1497), New York Tribeca (1883 textile factory, 16,000 square feet, opened 2012), Chicago (1902 factory), London (18th-century townhouse that was once JM Barrie’s home, 13,993 square feet, opened June 2021), Copenhagen (a former Carlsberg brewery building), a second New York location on the Upper East Side (former MoMA art storage warehouse, 9,600 square feet, opened March 2025), and now Toronto.
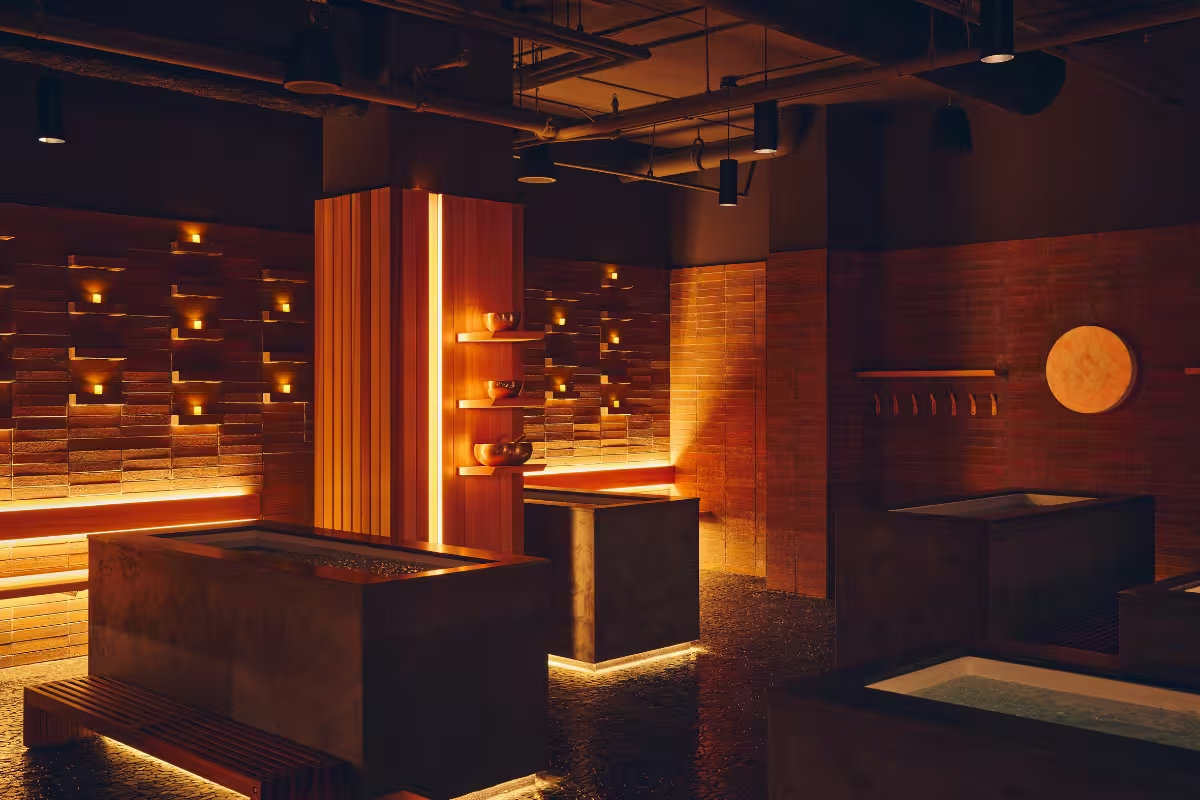
The Toronto location at 510A Front Street West occupies 23,000 square feet inside an Edwardian Classical building constructed in 1912 for the Copp Clark publishing company and now a designated heritage site. Two years of restoration. Exposed brick, imported pottery, candlelight. Nine thermal baths, twelve massage rooms, two heated marble beds. The space is designed for slow, self-directed circulation. There are no guided sessions, no facilitators leading breathwork, no DJ nights. When the New York Tribeca location opened, sessions were capped at 20 guests. The London location caps at 14 bathers simultaneously. The Upper East Side allows 16 guests per hour.
The pricing reflects the positioning. In Toronto, a 90-minute bath experience costs CAD $205 and includes a citrus scrub, eye patches, and a wellness shot, TheGATE reported this spring. A 45-minute massage with bath access runs $295. A couples package with a 60-minute massage runs $680. The Signature Wine Experience, a three-hour private wine bath with a body massage, a cranial massage, and a wine and cheese tasting, costs $1,560 per couple. Toronto also has its own exclusive ritual, the Boreal Forest Experience (pink salt exfoliation, cedar oil massage with jade stones, scalp massage, sparkling wine, chocolates, and forest berries).
AIRE does not sell memberships, and Serra told La Vanguardia in 2023 that the company was ruling out, for now, growth through franchises and hotel partnerships. The revenue model relies on a high average ticket from guests who visit a few times a year, not a few times a week, often paired with treatment upsells that can double the base price. The luxury hotel thermal suite trend runs on the same logic: low density, high perceived value, margin on ancillary services.
The revenue math
These two models produce radically different economic profiles.
AIRE disclosed financials to La Vanguardia for the fiscal year ending June 2023: €69.4 million in revenue, €25.1 million in EBITDA, a 36% margin, and 15% year-over-year growth. The company said it had doubled its pre-pandemic results. International locations (outside Spain) generated 72% of total revenue. At the time, AIRE employed 900 people across its portfolio; that number has since grown to more than 1,100.
For context, that €69.4 million (roughly $75 million USD) across eight mature locations at the time implies average revenue of roughly $9.4 million per location, though the actual distribution almost certainly skews toward the larger North American venues. Serra said in 2021 that AIRE locations usually reach 85 to 90% occupancy across the year.
Othership has not disclosed revenue. But the structure is visible. The Adelaide Street flagship (3,000 square feet) running four guided sessions a day at an average of 45 attendees and an average ticket of roughly CAD $55 (blending drop-ins and discounted members) would produce roughly $3.6 million annually. Revenue per square foot: roughly CAD $1,200. The larger Yorkville and New York locations should generate more in absolute terms, though the economics of venture-funded expansion (rising rent, facilitator payroll, marketing) consume cash differently than AIRE’s patient-capital model.
The capital requirements diverge sharply. Othership has raised about $18 million: a $1.3 million seed round a month after opening and an $8 million Series A in January 2023, according to The Logic, and about $8.5 million through a SAFE in 2025, per Athletech News, which reported that an investor in the round sees it as a step toward a Series B. Bent has told Spa Business the long-term goal is an Othership in every city in North America. That money expects a return timeline that heritage-restoration capital does not.
AIRE’s Toronto buildout required two years of heritage restoration. The company announced in 2023 a €55 million investment specifically for three North American locations (Upper East Side, Toronto, and a planned Los Angeles outpost), financed through bank credit and existing resources. For reference, the London location cost £11.5 million to build (roughly £822 per square foot), including a £600,000 overrun due to heritage building complexity, according to Professional Beauty. In January 2026, the investment firm Khemia took a minority stake to accelerate further international expansion.
Where each model breaks
Every operating model has a failure mode. For thermal wellness, the failure modes are model-specific, which means saturation risk is model-specific too.
The Othership model breaks when programming quality cannot scale. The guided session is the product. If the breathwork facilitator in Location 12 cannot deliver the same emotional intensity as the one in the Toronto flagship, the value proposition hollows out. We have seen this constraint at Sant Roch in Paris, where capacity discipline and facilitator quality are treated as the operating system, not a nice-to-have. At the scale Bent describes, Othership will need an institutional pipeline for training facilitators, and the company’s ability to do that will determine whether the model compounds or dilutes.
The venture capital structure adds a second pressure. If membership growth plateaus before the company reaches scale, the high-frequency model becomes a treadmill: lots of sessions, thin margins, rising rent, and investors expecting an exit. The closures already appearing in the broader market tell a cautionary story. MindZero, a South Carolina hot sauna and cold plunge chain, sought bankruptcy liquidation and closed its Mount Pleasant and Myrtle Beach studios in December 2025, according to The Post and Courier. Three franchisee-owned Restore Hyper Wellness studios in Colorado (Cherry Creek, Boulder and Erie) filed for Chapter 11 bankruptcy in January 2024, according to BusinessDen. Not every cold plunge and sauna venue will survive the shakeout. The high-volume wellness model is especially vulnerable when it runs ahead of local demand in secondary markets.
The AIRE model breaks on a different axis. Heritage buildings constrain expansion pace. You cannot franchise a restored 16th-century palace. Each new location requires years of site selection (Serra has said the search for the London site alone took more than two years), regulatory navigation, and custom construction. AIRE will never match the unit count of a venture-backed chain, and the company’s growth rate is structurally limited by the supply of suitable heritage buildings in target markets. Leases that typically run 25 years lock each bet into a long horizon.
The per-visit model also carries its own retention risk. AIRE does not need guests to come weekly, but it does need them to come back. A $205 to $1,560 experience that a guest books once and never repeats is tourism, not a business. The absence of a membership or loyalty structure means AIRE depends entirely on the experience being memorable enough to drive organic return visits and referrals. In a market where World Spa in Brooklyn has shown how to build repeat visitation at scale, the 85 to 90% occupancy Serra says AIRE locations usually reach suggests that return traffic is, in fact, materializing, but the model has little margin for error if a location underperforms. The 36% EBITDA margin only works at high occupancy.
What hotel and resort operators should take from this
The Othership-AIRE split maps directly onto a decision that hotel and resort developers are making right now: whether thermal wellness is an amenity (background feature, modest square footage, low staffing) or a revenue center (dedicated programming, trained facilitators, standalone economics).
Recent hospitality data adds a wrinkle. In 2024, hotels with major wellness programs earned 56% more total revenue per available room than hotels with minor ones, according to RLA Global’s Wellness Real Estate Report with HotStats, but they managed only 1% growth in gross operating profit per room, compared to 5% for hotels with minor wellness programs. The labor cost of programming-intensive wellness eats into the revenue premium. That is the Othership paradox in hotel form: more revenue, more staff, not necessarily more profit.
Accor’s 2025 wellness design white paper says about 4,300 square feet is enough for a “self-guided thermal and fitness experience, requiring no staffing.” That sounds more like AIRE than Othership. Low density, architectural investment, and an experience price point above $200 per person position thermal bathing as a destination feature rather than a facility amenity. This aligns with the trend we have tracked in luxury hotel thermal suites, where the thermal circuit becomes a reason to book the property, not a checkbox on the amenity list.
The Othership model argues for the opposite approach: thermal wellness as a revenue center with its own P&L. Guided programming, class schedules, membership structures, and community-building turn the sauna into something closer to a fitness studio that happens to use heat. Hotels experimenting with this approach can look at the Sauna House franchise model: a branded thermal wellness concept that could operate inside or next to a hotel, generate its own revenue, and draw foot traffic that the hotel’s restaurant and bar can capture.
The right choice depends on three things: capital structure (venture-scale investment versus patient capital), guest profile (repeat local visitors versus destination travelers), and operating DNA (can the property hire and retain facilitators, or is it better suited to a self-directed circuit?).
What does not work is splitting the difference. A thermal wellness facility that charges $120 per session but offers no programming and no architectural distinction sits in a dead zone: too expensive for habit-forming frequency, not memorable enough to justify an occasion. The Toronto experiment suggests the market is bifurcating, and operators who land in the middle may find they have built for neither audience.
The thermal wellness market is not one market. It is at least two, and the Othership-AIRE split in downtown Toronto is the clearest illustration available. One model sells frequency and community at a price point that demands venture capital and rapid scale. The other sells scarcity and architecture at a price point that demands patient capital and heritage real estate, and it reported €69.4 million in revenue at a 36% EBITDA margin for its fiscal year ended June 2023. Both can work. Both can fail. The failure modes are almost entirely non-overlapping. For hotel developers, resort operators, and wellness investors planning five to ten years ahead, the question is not whether thermal wellness works. It does. The question is which model fits the capital, the guest, and the building. The answer to that question determines everything else.
Othership and AIRE Ancient Baths are building opposite businesses in the same Toronto neighborhood. The contrast is not a rivalry. It is a market signal. Thermal wellness is splitting into a high-frequency, programming-driven category and a low-frequency, design-driven category, with distinct economics, distinct risks, and distinct paths to durability. Operators who understand which side of that split they belong on will build stronger businesses than those who try to be both.