14 of 16 Bathhouse and Thermal Sites Open 5+ Years Report $300K+ a Month; 1 of 9 New Ones Does
By Arlene Scott
Senior Wellness Correspondent & Hospitality Consultant
- Published
- Reading time
- 4 min
SaunaNews is published by SaunaShare, Inc., which also runs SaunaShare.com and SaunaMarketplace.com, where we sell many of the products we write about. Assume that experience shapes what we cover and what we don't. Who owns SaunaNews · The ownership announcement
Early results of a bathhouse benchmark run through two GWI initiatives: 71% of open sites report positive cash flow; 47% of respondents invested $2M or more.
In this story6 sections
Time in business shows up plainly in the early results of a new bathhouse benchmark. Of 16 respondents operating more than five years, 14 report average gross revenue of at least $300,000 a month. Of nine that opened in the past two years, one does.
The numbers are early findings from the 2026 Bathhouse & Thermal Wellness Development Benchmark Survey, published September 23 with 43 operators and industry participants responding. Cassandra Cavanah and Lisa Starr developed and run it through the Global Wellness Institute’s Hydrothermal and Consulting Initiatives, which helped them reach respondents. The survey is still open.
Most open sites report positive cash flow
Of the 34 respondents with a facility open, 24 (71%) report reaching positive cash flow. Fourteen of them got there within 12 months of opening.
Half of the operating respondents that shared revenue report average gross revenue of $300,000 or more a month, at least $3.6 million a year. Read that figure with the questionnaire in mind:
- $300,000 or more is the top answer on the survey’s revenue question, so a site grossing $300,000 a month and one grossing several times that land in the same box.
- The question covers each operator’s biggest or main facility, and it measures gross revenue, not profit.
- The early findings don’t give the result for sites open two to five years.
- The authors say the sample is too small to show that age causes the gap. Size, location, capacity and operating model all play a part.
Two public figures give a sense of scale. Bathhouse told CNBC it expects about $120 million in run-rate revenue by the end of 2026, a company-wide figure across several sites. A single site can make money well below the survey’s top bracket: Sauna House’s company-owned location in Asheville, North Carolina, reported 2023 gross revenue of $1,712,224, about $143,000 a month, and net profit of $867,205 (50.65%), or $701,105 (40.95%) after counting the royalty, brand fund and technology fees a franchisee would pay, according to the company’s 2024 franchise disclosure document.
Nearly half report $2 million or more to open
Twenty respondents (47%) report an opening investment of at least $2 million, and 15 (35%) report $5 million or more. That is the survey’s top investment answer, so the upper end is open. Of the respondents who gave a timeline, 56% took two years or longer to get from concept to opening.
For comparison, Sauna House’s franchise model estimates a total initial investment of $1,553,100 to $3,828,300 per location in the same 2024 disclosure.
Asked what prospective owners most often underestimate, respondents frequently cited:
- development and construction costs
- staffing and training
- permitting and regulatory requirements
- engineering and mechanical complexity
- ongoing operating costs
- the timeline to opening
Several of them, from construction costs to mechanical complexity, are covered in what bathhouse development actually requires.
Nearly two-thirds expect to run more than one site
Ten of the 43 respondents run two or more locations today. Sixty-five percent expect to within three years. The field is young: 63% of respondents aren’t open yet or have been operating five years or less, and 18 opened in the past two years or are still in development.
For makers of heaters, cabins, plunges and controls, that is a group of buyers planning more sites within three years.
Day passes still carry the model
Day passes and single visits were the most important way in for 20 respondents, more than any other access model. Twenty-eight (65%) named general admission and day-pass traffic as an important future revenue driver.
Memberships, private events, treatments, programming and food and beverage add revenue on top. For 53%, paid treatments are a core part of the business or an important second stream. Traffic still decides the economics for many.
Guided sessions and event saunas are gaining ground
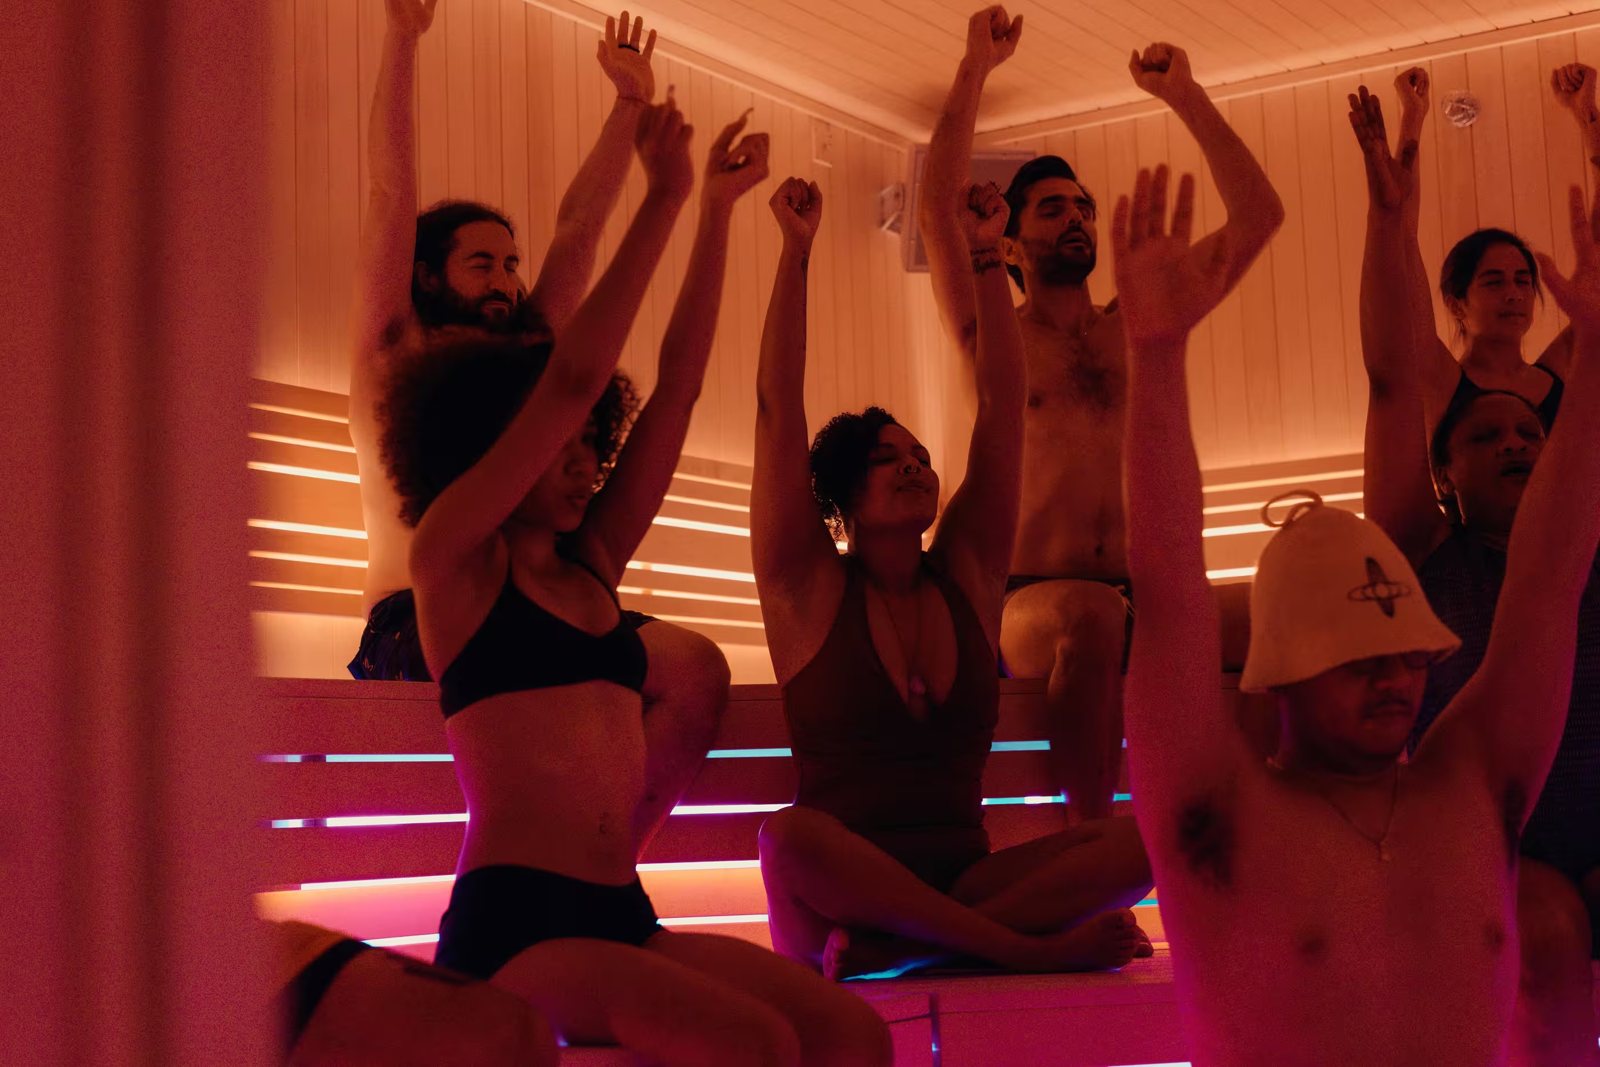
Seventy-seven percent of respondents offer guided sauna or thermal sessions or plan to. Sixty-five percent run a large-format event sauna or plan to add one.
Heat is the constraint in those big rooms. Commercial electric heaters sold in the US top out around 33 kW per heater. For the event sauna at Bathhouse’s Philadelphia site, EOS announced gas-fired systems of 120 kW and 60 kW.
The additions respondents mention most often:
- outdoor areas
- warm and vitality pools
- traditional saunas
- cold plunges
- food and beverage or a café
- large-format and event saunas
- private bathing or ritual suites
- treatment rooms
- steam rooms
Who answered
The 43 respondents include 24 standalone bathhouses or thermal wellness facilities and seven wellness or social clubs. The rest are hotel and resort spas, residential and mixed-use amenities, hot springs and other industry participants.
Most are North American, and Starr says the team wants more operators from other regions. Answers are self-reported ranges, and the authors won’t attribute them to any operator without permission. They call the results “directional rather than universal industry benchmarks.”
Using these numbers
- Model the ramp. Keep years one and two of a pro forma below the top revenue bracket. In this sample, one of nine sites under two years old had reached it, and the authors say new sites may need time to reach mature performance.
- Get six numbers in writing before you sign a lease: construction, staffing and training, permitting, mechanical engineering, operating costs and the opening timeline. Those are the items respondents frequently cited as underestimated.
- Cite it as early and directional. Call it Cavanah and Starr’s survey, run through the GWI Hydrothermal and Consulting Initiatives, with 43 respondents as of September 2026, and expect a lender or landlord to ask about the sample.
- Add your numbers. The survey takes eight to 10 minutes, and participants get early access to the findings. Every honest answer makes the benchmark better.